Building a custom luxury home in Central Oregon is a dream for many, but turning that vision into a tangible reality requires a solid financial foundation. For those embarking on a custom build in areas like Bend, Brasada Ranch, or Tetherow, understanding how to get a construction loan in Oregon is paramount. It's a different financial beast than a traditional mortgage, demanding a nuanced approach that accounts for local market dynamics, permitting complexities, and the specific needs of a high-desert custom build. As Kevin Rea, founder of Rea Co Homes, with over 45 years of experience and more than 100 custom homes built across Central Oregon (CCB #193427), I've guided countless clients through this intricate process.
Our award-winning work, including multiple Best of Show awards and the Earth Hero Award, isn't just about crafting exceptional homes; it's about providing an end-to-end, seamless experience, and that often begins with financing. Let's demystify the path to securing your construction loan.
Understanding Construction-to-Permanent Loans in Central Oregon
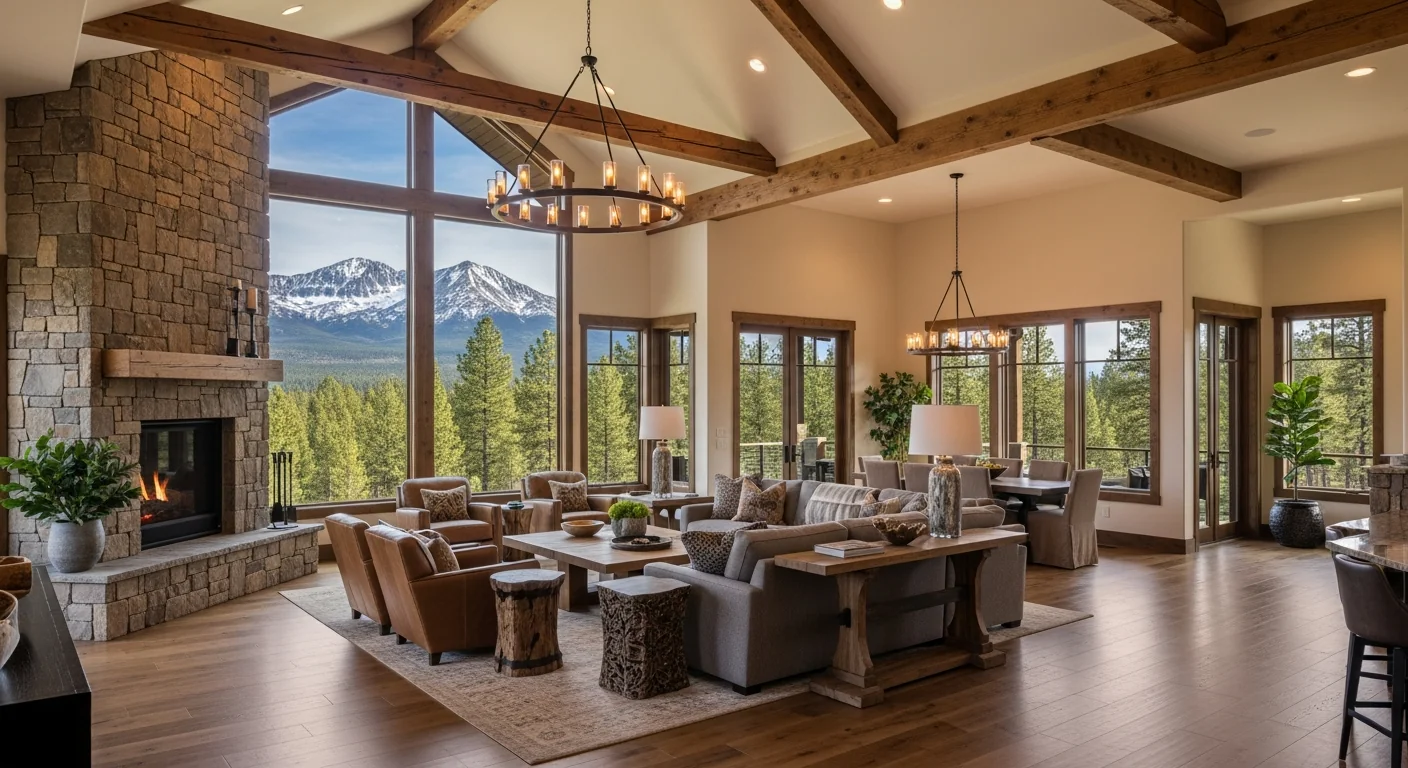
!Open-concept great room with timber beams and Cascade mountain views
Unlike a standard mortgage, which disburses funds at closing, a construction loan provides capital in stages, or 'draws,' as your home progresses. For luxury custom builds in Central Oregon, the most common and advantageous option is a construction to permanent loan Oregon offers. This type of loan rolls your construction financing directly into a permanent mortgage once construction is complete, saving you from a second closing and associated fees.
In my 45 years building custom homes, I’ve seen this structure consistently simplify the financial journey for our clients, especially when they're building in communities like Pronghorn or Broken Top where project scopes are often larger and more complex. It's designed to align with the phased nature of construction, with an initial approval based on your land, architectural plans, and a detailed construction contract with a reputable builder like Rea Co Homes.
Interest rates on construction loans are typically variable during the build phase, often tied to the prime rate. Once the home is complete, the loan converts to a fixed-rate or adjustable-rate permanent mortgage, locking in your long-term financing. This seamless transition is crucial for managing cash flow and providing peace of mind during a multi-month, often 18-26 month, build process for homes ranging from $1.5M to $6M+.
Essential Construction Loan Requirements for Oregon Lenders
Securing construction loan Bend Oregon 2026 financing, or anywhere in Central Oregon, involves meticulous preparation and a clear understanding of what lenders require. This isn't just about having good credit; it's about demonstrating project viability and your ability to manage a significant investment.
Here's what Oregon lenders typically look for:
- Strong Credit Score and Financial History: Expect lenders to require FICO scores generally above 700, and often higher for luxury custom builds. They'll scrutinize your debt-to-income ratio to ensure you can comfortably manage payments during and after construction.
- Significant Down Payment: While conventional mortgages might allow lower down payments, construction loans for custom homes often require 20-30% of the total project cost, including land. For a $3 million home, this means a $600,000 to $900,000 upfront investment. This shows strong borrower commitment and reduces lender risk.
- Detailed Construction Plans and Specifications: Lenders need approved blueprints, architectural renderings, and a comprehensive set of specifications. This is where partnering with an experienced builder like Rea Co Homes is invaluable. We provide the detailed documentation necessary to satisfy lender requirements, from structural plans to material selections, ensuring your estimated costs are accurate and thorough.
- Builder Vetting: Lenders will rigorously vet your builder. They'll examine their experience (our 45+ years and 100+ homes built speak volumes), financial stability, licensing (CCB #193427 is a must), insurance, and references. A proven track record of successful projects in Central Oregon is a significant advantage.
- Appraisal Based on Future Value: Unlike a traditional mortgage based on current value, a construction loan appraisal estimates the home's value upon completion. This 'as-completed' appraisal is critical for the lender to determine the loan amount. Our deep understanding of local market values in communities like Awbrey Butte, Sunriver, and Juniper Preserve ensures these appraisals accurately reflect the high quality and bespoke nature of our homes.
Selecting the Right Oregon Lender for Your Custom Home
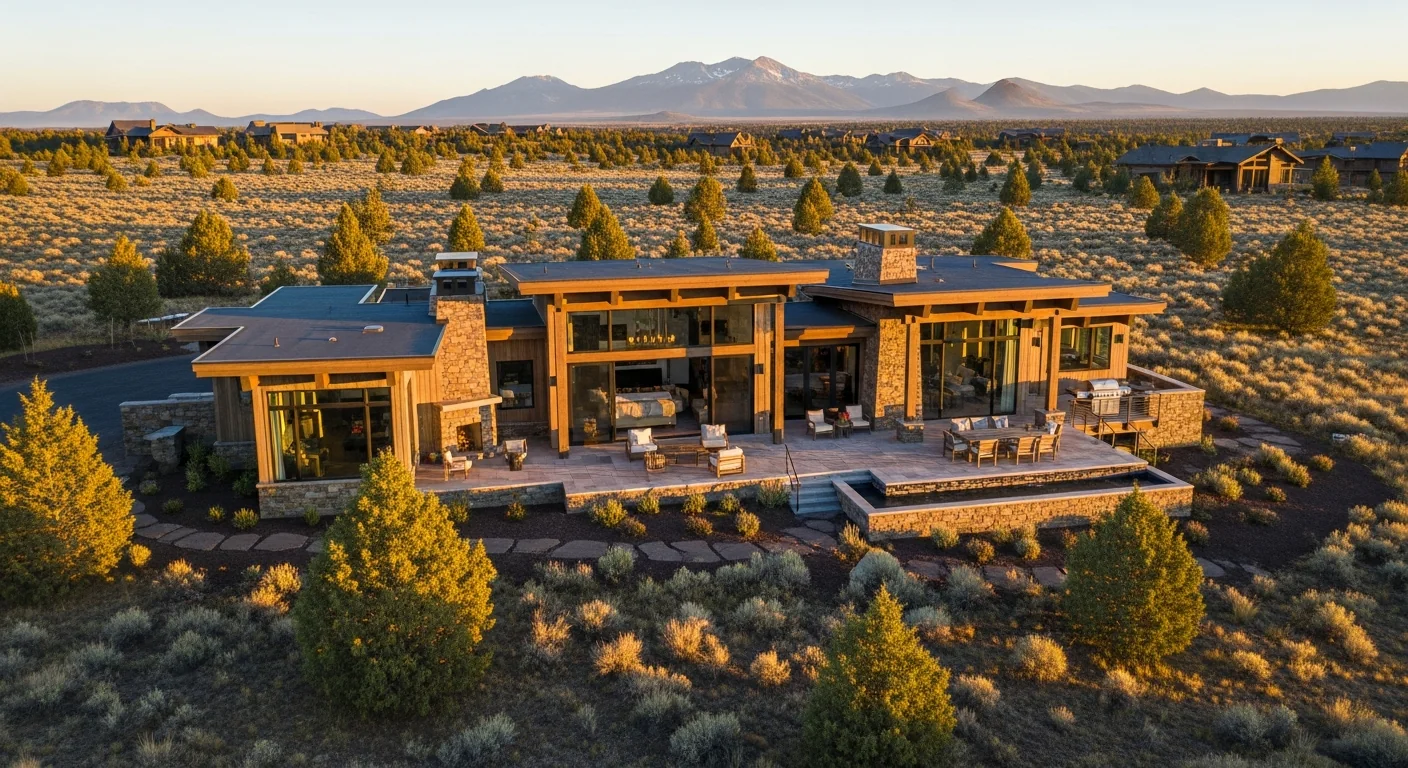
!Resort-style outdoor patio with Cascade views at luxury Oregon custom home
Choosing the right lending partner is as crucial as selecting your builder. Not all banks offer construction loans, and even fewer specialize in the unique demands of luxury custom home construction in a market like Central Oregon. Here are key considerations when looking for an Oregon lender:
- Local Expertise: A local lender understands Central Oregon's specific market conditions, appraisal nuances, and even local permitting processes. They are often more agile and attuned to the realities of building in areas like La Pine or Sisters, where site conditions or supply chains might differ from urban centers.
- Experience with Custom Home Construction: Inquire about their experience with construction-to-permanent loans for high-value custom builds. Ask for references from other builders or clients. A lender who frequently works with builders like Rea Co Homes will streamline the process significantly.
- Competitive Rates and Fees: Compare interest rates, origination fees, closing costs, and any administrative fees associated with draws. While the lowest rate is appealing, ensure the lender's service and expertise align with your project's needs.
- Flexibility and Communication: The construction process can have unexpected turns. A lender with a reputation for clear communication and some flexibility in draw schedules or change orders can be a tremendous asset. Clients often ask me about the draw process, and I always emphasize the importance of a responsive lending partner.
Kevin Rea has 45+ years of experience and has built 100+ homes across Central Oregon. For personalized guidance on financing a custom home build Central Oregon and connecting with the right lenders, call us at 541-390-9848 or email kevin@reacohomes.com.
The Construction Loan Application and Approval Process
The application process for a construction loan is more extensive than a typical mortgage. Here's a general overview of the steps involved:
- Pre-qualification/Pre-approval: Start here to understand your borrowing capacity. This often happens even before you've finalized your land or plans.
- Gather Documentation: You'll need financial statements, tax returns, employment verification, and a detailed construction contract with your builder, Rea Co Homes.
- Submit Formal Application: Once all documents are compiled, submit your formal application.
- Underwriting: The lender reviews all submitted information, performs credit checks, and evaluates the project's feasibility. This includes a thorough review of your builder's qualifications (CCB #193427 is a key trust signal). The lender will confirm all plans meet local building codes. For example, Bend's high desert elevation (3,600 ft) requires frost footings at minimum 24 inches depth under IRC 2021, a detail they'll verify in your plans.
- Appraisal: An 'as-completed' appraisal is conducted to estimate the future value of your custom home.
- Loan Approval and Closing: Upon approval, you'll close on the construction loan. This is when the land may be officially purchased (if not already owned), and the construction phase can begin.
Managing Your Construction Loan: Draws and Project Oversight
Once your construction loan is closed, the funds aren't simply handed over. They are disbursed incrementally through a 'draw schedule,' directly tied to the progress of your build. This protects both the lender and you, ensuring funds are used appropriately for the construction.
Typical Draw Schedule & Process
| Phase of Construction | Typical % of Loan Disbursed | Required Documentation for Draw |
|---|---|---|
| Foundation & Site Prep | 10-15% | Invoice, Inspection Report |
| Framing & Exterior Shell | 20-25% | Invoice, Framing Inspection |
| Rough-ins (Plumbing, Electrical, HVAC) | 20-25% | Invoice, Trade Permits & Inspections |
| Drywall & Interior Finishes | 15-20% | Invoice, Drywall Inspection |
| Exterior Finishes & Landscaping | 10-15% | Invoice, Exterior Completion |
| Final Completion & Punch List | 5-10% | Final Occupancy, Liens Waiver |
Each draw typically requires an inspection by the lender's representative to verify that the work has been completed to satisfaction and in accordance with the plans. This careful oversight is particularly important for luxury homes in communities like Caldera Springs, where material quality and craftsmanship are paramount.
On a recent Brasada Ranch project for a family relocating from Portland, we encountered an unexpected subsurface rock formation during excavation. This required specialized blasting and additional earthwork. Because we had built a strong relationship with the lender and maintained meticulous documentation, we were able to quickly communicate the necessary change order and secure approval for an adjusted draw, minimizing delays and keeping the project on track within the HOA's strict timelines for disturbance.
Navigating Central Oregon's Unique Challenges with Your Loan
Building in Central Oregon, while incredibly rewarding, comes with unique considerations that can impact your construction loan. These are not merely logistical; they can influence timelines and, by extension, your loan's interest accrual.
- Permitting Timelines: Deschutes County's permitting process, particularly for larger custom homes over 3,500 sq ft, can involve site plan review periods that run 8-12 weeks. Factor these into your overall project timeline, as funds won't start flowing until permits are secured.
- HOA Design Review Boards: Prestigious communities like Tetherow, Broken Top, and Pronghorn have rigorous Design Review Boards (DRBs). Their approval processes can add months to the pre-construction phase. For instance, Tetherow's DRB often requires multiple rounds of submissions, including precise material samples and color palettes, well before construction can commence. This impacts when you’ll need your initial loan draws.
- Seasonal Weather: Central Oregon's high-desert climate, with snowy winters, can sometimes cause temporary construction pauses or require specific construction techniques (e.g., winter concrete pours with special curing). A well-structured loan and a flexible builder account for these potential slowdowns.
- Supply Chain Logistics: While improving, supply chain disruptions can still affect lead times for specialized materials often used in luxury custom homes. We work diligently to pre-order and manage these logistics, but it's another reason to build in buffer time with your lender.
Why Partnering with an Expert Builder Matters for Loan Success
The seamless integration of your construction loan with your build process is largely dependent on your builder. As Rea Co Homes, we recognize that our role extends beyond construction; it's about facilitating your entire journey.
Our 45+ years of experience in Central Oregon means we understand:
- Accurate Cost Estimation: We provide detailed, realistic budgets that lenders trust, minimizing surprises that could impact your financing.
- Efficient Project Management: Our proven processes keep projects on schedule, ensuring draws are requested and disbursed promptly, aligning with your lender's requirements.
- Clear Communication: We act as the liaison between you, the architect, and the lender, providing necessary documentation and updates to keep your loan moving forward.
- Local Network: We have established relationships with local lenders who understand our quality of work and the Central Oregon market, simplifying the vetting process for you.
From the initial concept to the final touches, Rea Co Homes is dedicated to making your custom home journey in Bend, Redmond, or any Central Oregon community an exceptional one. We help clients navigate how to get a construction loan in Oregon with confidence, translating complex financial steps into clear, actionable progress.
Frequently Asked Questions
What are the typical interest rates for construction loans in Central Oregon?
Interest rates for construction loans in Central Oregon are typically variable during the construction phase, often tied to the prime rate plus a margin. This means rates can fluctuate until the loan converts to a permanent mortgage. As of late 2023/early 2024, these rates generally range from 7-9% but are subject to market changes. Once construction is complete, a construction-to-permanent loan will typically convert to a fixed-rate mortgage with rates more aligned with current traditional mortgage rates. It's crucial to discuss current market rates and potential rate lock options with your chosen Oregon lender, especially given the anticipated market shifts for construction loan Bend Oregon 2026.
Can I use my own land as a down payment for a construction loan?
Yes, if you already own the land for your custom home in Central Oregon, its appraised value can often be used as part or all of your required down payment. Lenders will typically value your land at the lower of its purchase price or current appraised value. This can significantly reduce the cash you need to bring to the table upfront. This is a common scenario for clients building in established communities like Awbrey Butte or Prineville, where they may have owned their lot for some time. Always discuss this strategy with your lender early in the process.
What are common pitfalls to avoid when getting a construction loan in Oregon?
One of the most significant pitfalls is underestimating the total project cost, including soft costs like architectural fees, permits, and landscaping. An inaccurate budget can lead to cost overruns and require additional financing, which can be challenging to secure mid-project. Another pitfall is choosing an unvetted builder; lenders rely on the builder's reputation and financial stability. Finally, neglecting to factor in Central Oregon-specific delays, such as extended permitting timelines in Deschutes County or HOA design review processes in communities like Tetherow, can strain your budget and timeline. Partnering with an experienced builder like Rea Co Homes (CCB #193427) mitigates these risks.
How long does the construction loan approval process take in Oregon?
The construction loan approval process in Oregon can vary, but generally, it takes longer than a standard mortgage due to the extensive documentation and vetting involved. From initial application to closing, expect it to take anywhere from 45 to 90 days. This timeline can be influenced by how quickly you provide necessary documentation, the complexity of your project (e.g., a multi-million dollar custom home in Broken Top vs. a smaller build), and the lender's current volume. Having all your plans, permits (or clear permit application timelines), and builder contract (from an award-winning builder like Kevin Rea) ready will significantly expedite the process.
Navigating how to get a construction loan in Oregon for your custom luxury home is a significant undertaking, but with the right guidance, it’s a clear path to building your dream. Rea Co Homes is here to provide that expertise, ensuring your financial journey is as solid as the foundation of your new Central Oregon home.
Ready to discuss your custom home vision and the financing options available? Contact Kevin Rea directly at 541-390-9848 or kevin@reacohomes.com. Our team at Rea Co Homes is committed to excellence, from groundbreaking to move-in, consistently delivering award-winning results and an unparalleled building experience.